news & Insights
Who Owns The Block?
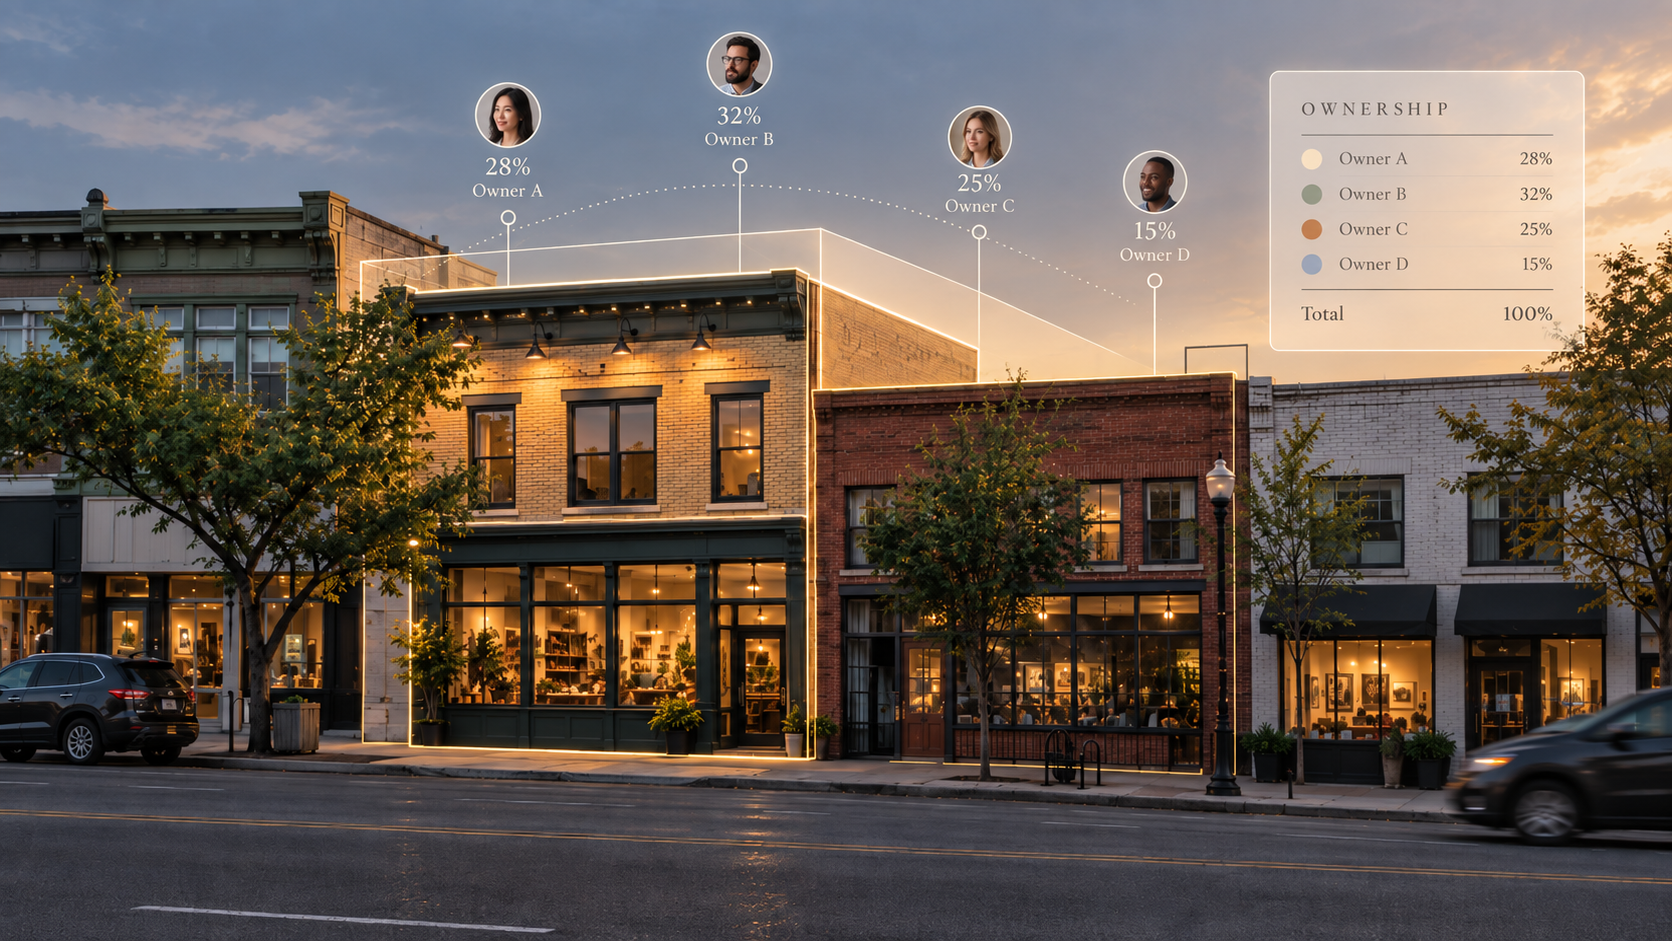
Who owns what community development builds?
Community development can be measured. In mid-2025, 1,378 certified community development financial institutions held $446 billion in assets. Banks reported $138.4 billion in community development lending in 2024.
Now ask a different question. How much of the commercial property in a neighborhood is owned by the people who live around it, and how much wealth has that ownership built for them?
No one can answer. There is no registry, no reporting standard and no annual number. Capital allocates to what it can see, and this category is nearly invisible.
Naming it precisely
Community ownership now covers a wide range of arrangements. Some give residents a voice. Some deliver affordability. Fewer give an individual an appreciating economic interest that can be held and eventually realized. We reserve the term for that last one, because wealth is the question.
Measured that way, the field is small. Chicago TREND owns seven shopping centers with $44 million under management. Portland's Community Investment Trust lets residents invest $10 to $100 a month in a commercial property. Market Creek Plaza in San Diego transferred a 20 percent stake to more than 400 residents in 2006 and still operates, with hard lessons about what it costs to govern an asset after the offering closes.
Why the numbers stay small
The tools that built this field finance development. Tax credit compliance periods end. Loans are repaid and lent again. The output is buildings, housing, businesses and services. A permanent local balance sheet owned by residents was never the product.
The assets are already here
Churches, community development corporations, neighborhood organizations and legacy nonprofits own buildings, lots and storefronts across West and South Louisville. One at a time, those assets are hard to finance, insure and manage well. Held together, they are a portfolio.
Institutional real estate has pooled property this way for decades. An owner contributes a building and receives an interest in the larger portfolio instead of cash. In affordable housing, Joint Ownership Entity New York City has aggregated more than 2,700 contributed units. We found no example of that mechanism used to build individual wealth through neighborhood commercial property.
Pooling is the tactic. Ownership is the objective.
The point of all of this is wealth on a household balance sheet. Residents putting in $10 or $100 a month cannot assemble a commercial portfolio on their own, and a single building is a fragile place to hold a family's savings. Market Creek showed what happens when the asset underneath resident ownership cannot carry it. Start instead with a portfolio that is diversified, financeable and professionally managed, and there is something durable for residents to own a piece of. Contributed property is how you get there without waiting years to raise a purchase price.
The order matters. Build the thing that can hold wealth, then invite people into it.
Rising Roots Collective, filed as a Kentucky limited cooperative association in July, is testing whether it can be. Center for Neighborhoods serves as fiscal sponsor and manager. It is early, and we are careful about what we claim. More detail and data is available in a white paper entitled Who Owns What Community Development Builds, which is available on request.
Get in touch
We are beginning to share this work with practitioners, community groups and funders. If you are building community ownership, wondering whether your organization's property could work harder inside a shared portfolio, or thinking about funding this work, please get in touch.
share this
Be Part of
the Story
The stories you’re reading are powered by residents building stronger communities. Donate today and support our residents, plans, and partnerships that make community-led change possible.